529 Plans & Estate Planning in Alabama
You’re thinking about your daughter’s future. She’s six and started first grade. Or she’s sixteen and you’re wondering if the savings you’ve built will be enough.
College tuition has quadrupled since I went to school. The average in-state public university now costs over $25,000 per year when you include room, board, and expenses. Private schools easily hit $60,000 or more.
The 529 plan is the best tax-advantaged tool for education savings. But most parents don’t realize how it interacts with estate planning. Done wrong, your 529 money creates problems you never intended.
The Scenario That Catches Families Off Guard
Consider this scenario: A husband, fifty-two years old, dies unexpectedly. He and his wife had two 529 plans for their kids, each with about $80,000.
Here’s what they didn’t know: he was the sole owner on both accounts. He never named a successor owner. Under Alabama law, those 529 accounts became part of his probate estate.
The accounts stayed locked while probate was open. The family had to pay spring semester out of cash flow. It took eight months to get court approval to transfer ownership to his wife.
All because of a checkbox on a form.
What Is a 529 Plan?
A 529 plan is an investment account designed for education expenses. You contribute after-tax money. It grows tax-free. Withdrawals for qualified education expenses are completely tax-free.
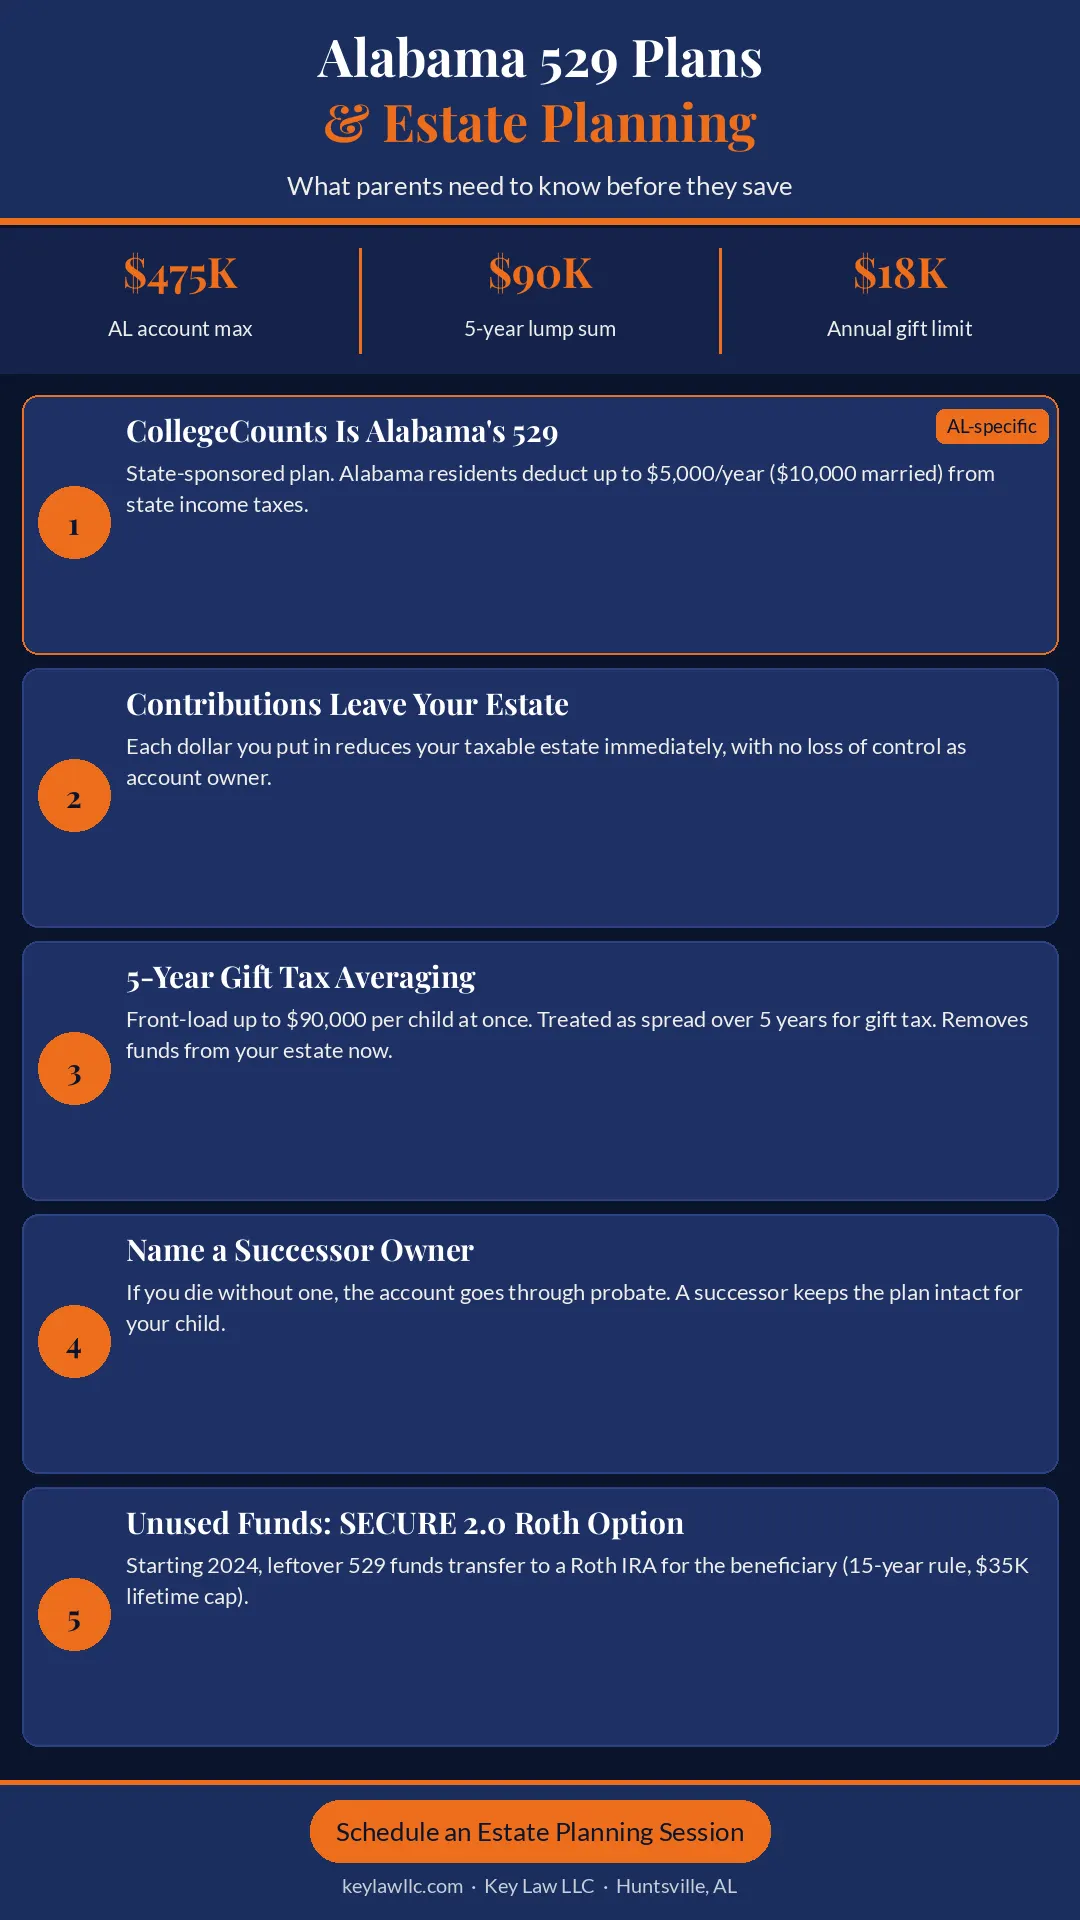
Alabama has its own plan called CollegeCounts. Alabama residents get an additional benefit: state income tax deductions for contributions. Up to $5,000 per year for individuals, $10,000 for married couples filing jointly.
That’s real money. At 5% state income tax, a married couple contributing the maximum saves $500 per year in state taxes. Over eighteen years, that’s $9,000 in tax savings for doing what you were going to do anyway.
How Do 529 Plans Fit Into Estate Planning?
Most people think of 529 plans as pure education savings. They are also effective estate planning tools.
Contributions to a 529 plan are completed gifts for tax purposes. That means they leave your estate immediately, even though you keep control as account owner.
You contribute up to $18,000 per year per beneficiary without using any of your lifetime gift tax exemption. Married couples contribute $36,000 per beneficiary.
Or you front-load five years at once: $90,000 per beneficiary ($180,000 for married couples). This uses your gift tax exemption spread over five years. It removes that money from your estate immediately while letting the investments compound tax-free for decades.
I’ve seen grandparents use this to shift significant wealth to grandchildren while reducing their estate tax exposure.
What Are the Alabama-Specific Rules?
Alabama’s plan has some quirks you need to know.
The state tax deduction is only for contributions to CollegeCounts, not to 529 plans from other states. If you use a plan from another state because you like their investment options, you lose the Alabama deduction.
Total account balances are capped at $475,000 per beneficiary across all Alabama 529 accounts. Once you hit that limit, you don’t contribute more, though earnings push the balance higher.
And unlike some states, Alabama doesn’t allow tax-free withdrawals for K-12 expenses like private school tuition. Federal law allows it up to $10,000 per year, but Alabama doesn’t give you the state tax benefit for money used that way.
Successor Ownership: The Critical Step
Every 529 account needs a successor owner. This is the person who takes over when you die.
Without a successor owner, the account becomes part of your estate. That means probate. That means court. That means potentially months before anyone accesses the money for tuition payments.
The successor owner is anyone you choose. Usually it’s the surviving spouse. But I’ve seen situations where grandparents are owners and name the child’s parent as successor. Or where one parent names the other, and also names a backup like a trusted sibling in case both parents die.
Review your 529 accounts annually. Make sure the successor owner designation matches your current estate plan. Life changes. Divorce happens. People die. Your 529 account needs to keep up.
The One Mistake Nobody Talks About
There’s a strategy I’m seeing pushed online: put money in a 529 plan, then immediately withdraw it for non-education expenses. The thinking is you get the state tax deduction, then use the money for anything you want.
This is wrong. The penalty is steep.
Non-qualified withdrawals lose the tax-free growth. You pay ordinary income tax plus a 10% penalty on the earnings portion. And Alabama will recapture any state tax deduction you took.
I’ve seen people try this because they needed cash for an emergency and thought they’d outsmart the system. It cost them thousands in taxes and penalties. The tax deduction wasn’t worth it.
There’s a narrow exception for scholarships. If your child gets a full ride and doesn’t need the 529 money, you withdraw up to the scholarship amount penalty-free (but you still pay income tax on the earnings).
What to Do Next
If you have 529 plans, log in today and check your successor owner designation. If it’s blank, fix it now. This takes five minutes and prevents months of probate court.
Consider whether front-loading contributions makes sense for your estate planning. Removing $180,000 from a taxable estate while keeping control as owner is a strong combination.
And coordinate your 529 plans with your overall estate plan. They should work together with your living trust, life insurance, and other tools. Not against them.
Schedule a free 30-minute consultation to review how your education savings fit into your complete estate plan. I’ll make sure your kids’ college money doesn’t create legal headaches.
Call (256) 715-5711 or email contact@keylawllc.com.
Frequently Asked Questions
What is a 529 plan in Alabama?
A 529 plan is a tax-advantaged savings account for education expenses. Alabama’s plan is called CollegeCounts. Contributions grow tax-free, and withdrawals for qualified education expenses are not taxed. Alabama residents also get a state income tax deduction for contributions up to $5,000 per year ($10,000 for married couples filing jointly).
How much do you contribute to a 529 plan in Alabama?
Alabama’s CollegeCounts 529 plan has no specific annual contribution limit, but total account balances are capped at $475,000 per beneficiary. For estate planning purposes, you contribute up to $18,000 per year ($36,000 for married couples) per beneficiary without gift tax consequences, or make a lump sum contribution of up to $90,000 ($180,000 married) using the 5-year gift tax averaging rule.
Do 529 plans affect financial aid eligibility?
Yes, but the impact is limited. Parent-owned 529 plans are treated as parental assets on the FAFSA, reducing aid by up to 5.64% of the account value. Distributions from parent-owned plans don’t count as income to the student. Grandparent-owned plans previously hurt aid more, but recent FAFSA changes have reduced that impact.
What happens to a 529 plan if the account owner dies?
The account passes to a named successor owner. If no successor owner is named, the account becomes part of the deceased owner’s estate. This is why naming a successor owner is critical in your estate plan. Without one, the plan goes through probate or loses its tax-advantaged status during estate administration.
Does Alabama allow tax-free 529 withdrawals for K-12 expenses?
Federal law allows up to $10,000 per year for K-12 tuition at public, private, or religious schools. Alabama state law, though, does not provide state income tax deductions for K-12 contributions like some states do. You still get federal tax-free growth, but you lose the Alabama state tax benefit for K-12 savings.
How does the 5-year gift tax averaging rule work for 529 plans?
The IRS allows you to front-load up to five years of annual gift tax exclusion contributions into a 529 plan at once. For 2026, that means a single contributor deposits up to $90,000 per beneficiary ($180,000 for married couples) in one year. The contribution is treated as spread over five years for gift tax purposes, removing that money from your taxable estate immediately while keeping full control as account owner.